
ESRS E3 Water Disclosure in the GCC: What Boards Need to Know
ESRS E3 is the European standard covering water and marine resources. It requires companies to report water withdrawal, discharge, consumption, recycled and reused volumes and water intensity, with separate disclosure for sites located in areas of high water stress. For companies operating in the GCC, nearly every site meets that definition, which changes the shape of the disclosure rather than adding a footnote to it. A second consideration applies regionally: because most Gulf water is produced by desalination, purchased water also carries embedded emissions that belong in the value chain inventory.
Key takeaways
- ESRS E3 asks for five things: a water policy, actions, quantified targets, metrics and the anticipated financial effects of water risk.
- In the GCC, high water stress is the norm rather than the exception, so the stressed-area breakout becomes the primary disclosure.
- Desalinated water carries a measurable carbon footprint, which places purchased water in Scope 3 as well as in ESRS E3.
- Most GCC companies will meet these requirements through customer, lender and exchange expectations rather than through direct regulation.
- The anticipated financial effects disclosure, ESRS E3-5, is the requirement we see prepared least often.
Why water is becoming a board-level topic
Water is moving from an operational cost line to a disclosed, financed and investor-visible metric, and the regional calendar is accelerating that shift.
The UAE will host the 2026 UN Water Conference in Abu Dhabi from 8 to 10 December, co-hosted with Senegal. It is the third conference of its kind since 1977 and the first dedicated to Sustainable Development Goal 6 on water and sanitation. Its programme includes six interactive dialogues, one of which addresses investment and financing.
The practical implication for companies is straightforward. Discussion of private capital in water infrastructure raises the standard of evidence expected from participants. Organisations seeking a tariff arrangement, an offtake, a site allocation or a sustainability-linked loan will increasingly be asked to describe their own water position in auditable numbers.
Capital is already committed. The Middle East spent USD 53.4 billion on desalination capacity between 2006 and 2024, close to half of global capital expenditure in the sector over that period.
What ESRS E3 requires
ESRS E3 sets out five disclosure requirements, published in full on the EFRAG Knowledge Hub.
E3-1 Policies. A water policy, including commitments at site or basin level. Where a site sits in a high water stress area and no policy covers it, the company must state that and explain why.
E3-2 Actions. The measures taken and the resources allocated to them, linked to measured volumes rather than described in general terms.
E3-3 Targets. Quantified targets, contextualised to the catchment in which the company operates.
E3-4 Metrics. Water consumption, withdrawal, discharge, recycled and reused volumes, and intensity per unit of revenue.
E3-5 Financial effects. The anticipated financial effects of water-related risks over the medium and long term.
Has the Omnibus simplification changed this?
The Corporate Sustainability Reporting Directive (CSRD) and its standards have been narrowed rather than withdrawn. The European Commission adopted delegated acts revising the ESRS, together with a voluntary reporting standard, on 3 July 2026; barring objection, the Parliament and Council’s scrutiny period is expected to close in early September 2026, after which the acts await publication in the Official Journal before taking legal effect. The revised standards reduce the number of data points and drop the water intensity metric, but E3 retains its consumption metrics, its high water stress breakout and its recycling volumes.
Mandatory scope now generally applies to EU undertakings exceeding both 1,000 employees and EUR 450 million net turnover, with a separate test for third-country groups based on EU turnover and the presence of an EU branch or subsidiary. Large Gulf groups with significant European revenue can therefore fall in scope directly. The majority will encounter these requirements indirectly, through European customers, banks and auditors, in the same way Scope 3 requirements reached the region. Our post on Scope 3 Category 1 for GCC builders describes how that pattern developed in construction.
Why the water stress screen behaves differently in the GCC
ESRS E3 distinguishes between ordinary sites and sites in areas at water risk, including areas of high water stress. Assurance providers expect that screen to be run against a recognised water risk atlas, most commonly WRI Aqueduct, with the version and baseline year recorded.
Applied across a Gulf portfolio, the distinction largely disappears. Almost every catchment in the region classifies as extremely high stress. Three consequences follow for the disclosure.
The stressed-area breakout ceases to be a subset and becomes the whole figure, which raises the expected level of detail on sources, recycling and site-level performance. Group-level reduction targets delivered outside the region are difficult to defend where regional consumption is growing. And the requirement to declare the absence of a policy applies broadly rather than exceptionally, since many groups do not yet hold a water policy covering their Gulf sites.
The link between water and emissions
Water and carbon reporting are connected in this region in a way they are not in most others.
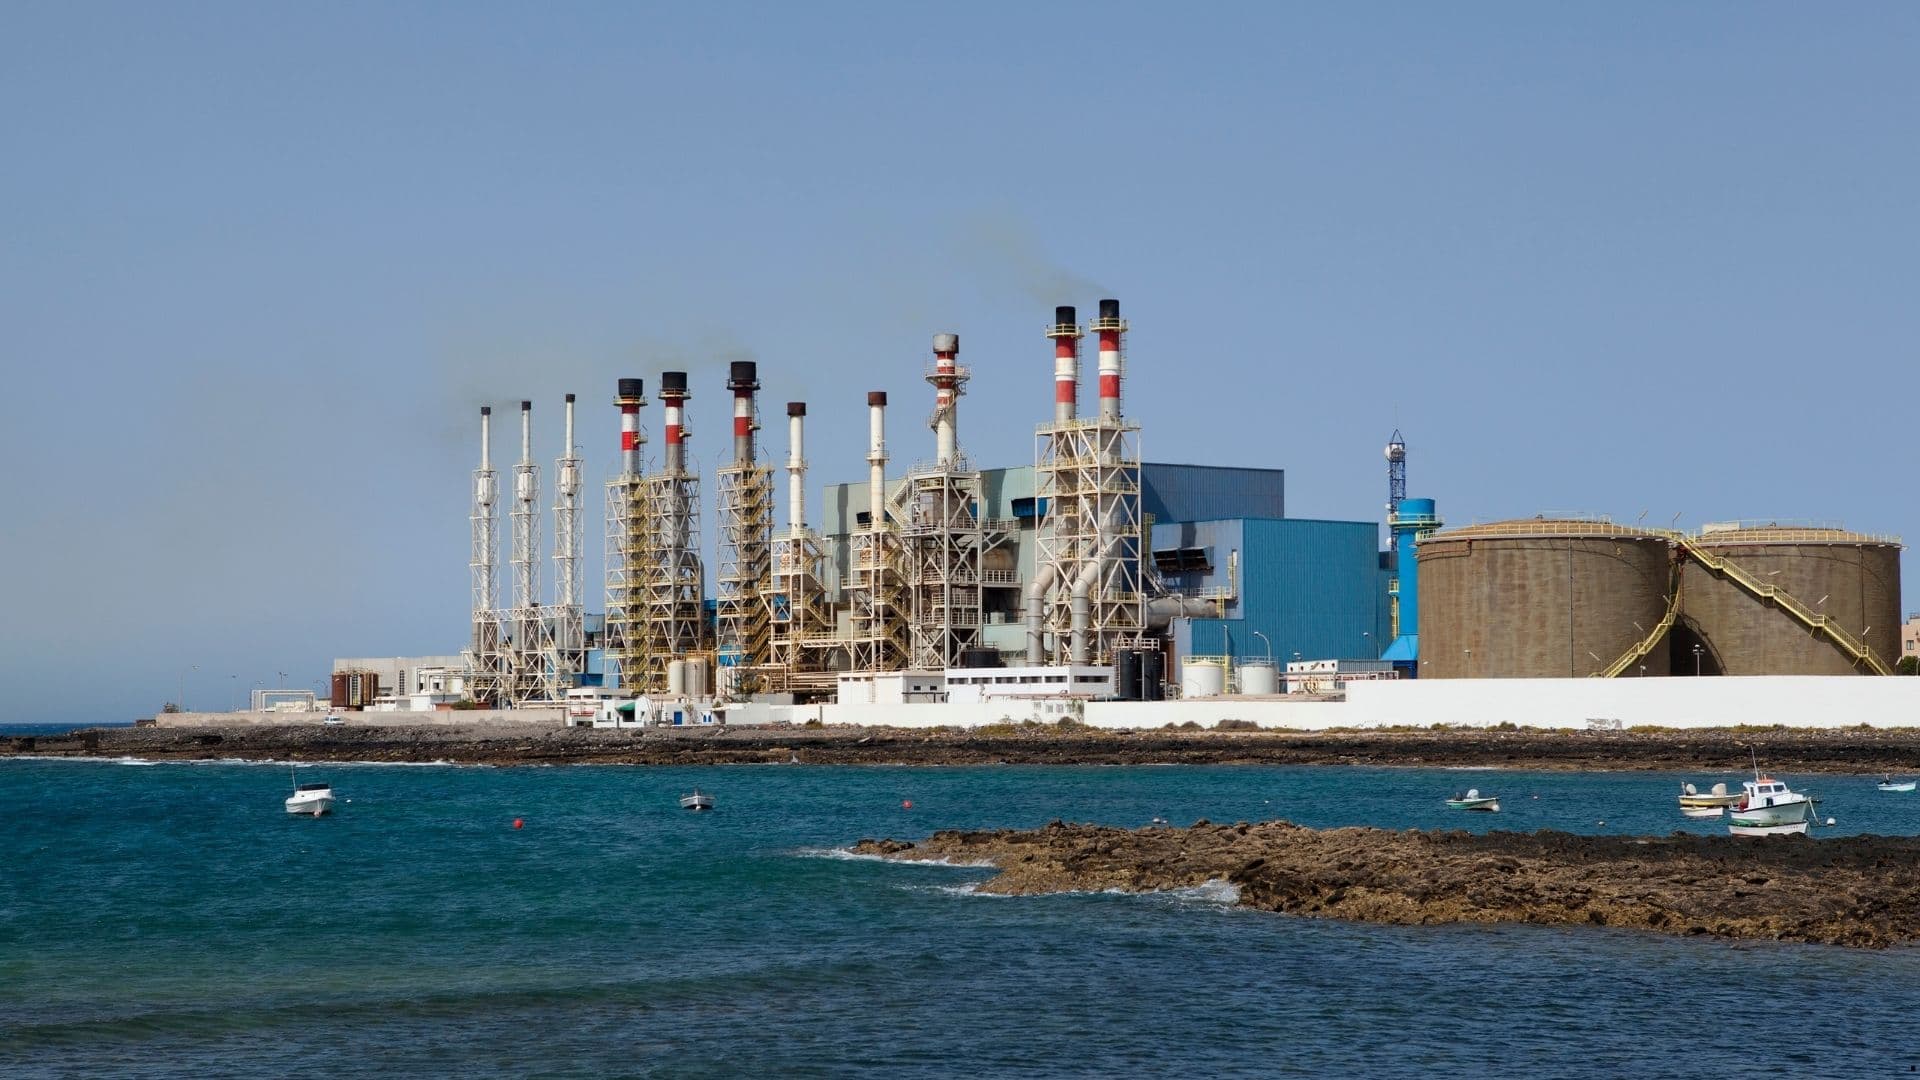
A substantial share of Gulf municipal supply is produced by desalination, and the Middle East and North Africa holds approximately half of global desalination capacity. That water is produced using energy, predominantly gas. Published estimates place reverse osmosis near 2.3 kgCO2e per cubic metre and gas-fired thermal desalination near 9 kgCO2e per cubic metre.
Two implications follow. First, purchased water is a purchased good, so its embedded emissions belong in Scope 3 Category 1 under the GHG Protocol Corporate Value Chain (Scope 3) Standard, and the factor applied should reflect the supplying technology rather than a global average. Second, where power and water are co-produced at the same plant, the method used to allocate fuel and emissions between the two outputs affects both the Scope 2 factor and the water factor, which is a matter for documented methodology rather than assumption.
Related environmental effects sit outside E3. Brine discharge, for example, falls under ESRS E2 on pollution and E4 on biodiversity, which is one reason a regional water disclosure requires input from more than one function.
Where the pressure lands first
Six sectors are most exposed in the GCC:
- Data centres and digital infrastructure, where cooling volumes are large and capacity is being added quickly.
- Hospitality and tourism, where consumption per guest is high and rarely disclosed.
- Food, beverage and agriculture, with the most significant value chain exposure.
- Petrochemicals and heavy industry, where both process water and discharge quality are material.
- Real estate and construction, where consumption is distributed across many sites and often unmetered.
- Healthcare, where sterilisation and cooling loads are significant. See our post on healthcare emissions in the GCC.
Listed companies face a nearer-term prompt. The unified ESG metrics agreed across GCC exchanges include water, and ADX’s ESG disclosure guidance lists water use alongside emissions and energy.
What a defensible water disclosure requires
Five foundations, in order of dependency:
- A site register with stress classification. Each facility recorded with its catchment and baseline stress rating from a recognised atlas, evidenced and dated.
- A source split rather than a single total. Desalinated supply, treated sewage effluent, groundwater, tanker deliveries and recycled internal flows carry different footprints and should be reported separately.
- Metrics defined as the standard defines them. Consumption is withdrawal minus discharge, not the invoiced volume, which means discharge has to be measured.
- Intensity metrics the business manages to. Cubic metres per million of revenue is the current ESRS default, though the revised standard due for 2027 reporting drops it; an operational denominator such as per room night, per tonne of product or per megawatt hour of IT load keeps the figure usable either way.
- A modelled view of financial effects. Tariff exposure multiplied by projected volume converts water from an environmental metric into a cost line with a trajectory, which is what E3-5 asks for.
How Coral supports water reporting
Coral’s multi-framework ESG reporting module covers ESRS E3 water and marine resources, including consumption, quality and discharge, within the same workflow that produces E1 climate disclosures, and maps to the GRI Topic Standards for organisations reporting under GRI. Double materiality is assessed across all Environmental, Social and Governance topics rather than climate alone.
In practice this means facility-level scoping so stressed sites can be separated and consolidated, evidence carried from source document through to disclosure, human review and approval gates before figures are accepted, and group consolidation with provenance preserved from subsidiary to parent. The same data lineage that allows an emissions inventory to withstand verification applies to water, an argument set out in our post on building a GHG inventory that survives a verifier.
Frequently asked questions
Is water disclosure mandatory for companies in the UAE and Saudi Arabia?
Not at federal level in the way emissions reporting is. The UAE Climate Law addresses greenhouse gases rather than water. Water requirements reach Gulf companies through stock exchange ESG guidance, European customers subject to the CSRD, lenders and supplier questionnaires.
Does ESRS E3 still apply after the Omnibus simplification?
Yes. The revised standards reduce the number of required data points and rely more heavily on materiality, but E3 retains its consumption metrics, high water stress breakout and recycling volumes, though the water intensity metric is dropped. The Commission adopted the revised delegated acts on 3 July 2026; barring objection, EU scrutiny is expected to close by early September 2026, after which they await Official Journal publication.
How should a company report water when every site is in a high water stress area?
Report the full volume as stressed-area consumption, then differentiate by source, by recycled share and by site-level intensity. The requirement is met through evidence and granularity rather than through the presence of a low-stress comparison group.
Should the emissions of desalinated water be reported in Scope 1, 2 or 3?
Purchased desalinated water is a purchased good, so its embedded emissions belong in Scope 3 Category 1. Where a company operates its own desalination unit, the fuel is Scope 1 and the purchased electricity is Scope 2.
What is the most common weakness in a first water disclosure?
A single annual total taken from utility invoices, with no discharge measurement, no source split and no recycled volume reported. It provides no basis for a target and little for an assurance provider to test.
Next step
Book a demo to see how ESRS E3 water disclosures and Scope 1, 2 and 3 emissions are produced from the same evidence base in Coral, or review the regulations we support.
Related Articles
Saudi Arabia’s 2GW Battery Storage Deal and the Scope 2 Accounting Gap